Unhealthy Competition in Life Insurance Business: Today's Growth or Tomorrow's Challenge?
Nepal's life insurance sector expanded in fiscal year 2081/82 with Rs. 182.27 billion in premiums and 39.99 percent population penetration. However, unhealthy competition, as highlighted by the Insurance Authority, could pose long-term risks to the industry, companies, agents, and policyholders. This article analyzes the distinction between healthy and unhealthy competition and its multidimensional impact.
The life insurance business in Nepal is expanding. With the growing reach of insurance companies, branch networks, number of agents, and diversity of insurance services, public access to insurance has also widened.
According to the Nepal Insurance Authority, in fiscal year 2081/82, total life insurance premiums reached Rs. 182.27 billion. During the same period, life insurance population penetration reached 39.99 percent. The life insurance sector also made investments worth Rs. 759.66 billion, demonstrating its importance to the economy.
While these figures are encouraging, the future journey of the life insurance business should not be limited to merely increasing the size of the business. It is not just about how much the business grew, but what kind of business grew, how long it lasted, how satisfied agents and policyholders are, and how much long-term financial security it is providing—these questions are even more important.
Competition is Necessary, But What Kind?
Competition is a natural process of a market economy. Competition encourages companies to develop better services, technology, products, and the experience of policyholders and agents. The Insurance Authority's own objectives also mention providing quality insurance services through healthy competition by making the insurance business organized, regular, competitive, and reliable.
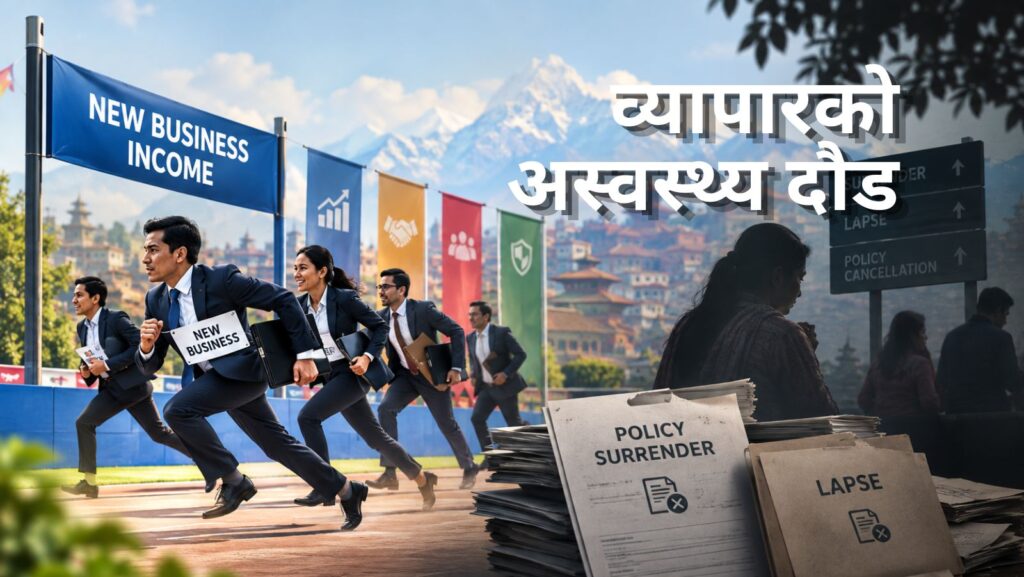
However, if competition becomes focused not on creating new markets and improving service quality but on a race to shift existing policyholders, agents, or business from one company to another, then its long-term impact must be considered. Life insurance is different from many other businesses. It is not just a transaction of 1–2 years; it is a financial contract between the policyholder and the company that can last for decades. Therefore, the true quality of today's sale may only become apparent many years later.
Unhealthy Competition: A Challenge for the Life Insurance Industry
The Insurance Authority itself has identified unhealthy competition among insurers as one of the challenges in the insurance market. Additionally, the Authority has pointed out that improvements are needed in governance, risk assessment, market research, claim settlement, employee training, and other institutional aspects in the life insurance sector. This should not be understood merely as a matter of business competition between two companies. The impact of unhealthy competition can gradually reach the entire industry, companies, employees, agents, and ultimately the policyholders.
1. Impact on the Overall Insurance Industry
The biggest risk of unhealthy competition is that it can weaken the business culture and credibility of the entire industry. If companies focus on pulling each other's existing business rather than creating new markets, the actual expansion of the overall insurance market may slow down.
Competition that makes the same customer switch companies may change the size of a company's business for some time, but it does not necessarily add new policyholders and expand insurance access. Similarly, excessively target-focused competition creates an environment that prioritizes quantity-oriented business over quality business. This creates challenges in policy continuity, policyholder satisfaction, claim experience, and long-term business stability. In the long run, such a trend also increases the risk of life insurance being understood merely as a product for sale rather than a means of financial security.
2. Impact on Companies
Unhealthy competition increases a company's costs, risks, and managerial pressure. As pressure to maintain or increase market share grows, companies may have to spend more than expected on branch expansion, sales incentives, agent management, publicity, and other areas. However, if quality and long-term business are not created in proportion to the expenditure, its impact falls on the company's financial performance.
On the other hand, giving excessive importance to immediate business targets can overshadow long-term foundations such as risk assessment, market research, product development, employee development, customer service, and institutional governance. The Insurance Authority has also mentioned that on-site monitoring of life insurance companies has revealed weaknesses in financial and medical risk assessment, lack of adequate market research, insufficient investment in employee training, and challenges in the effective implementation of claim settlement arrangements. Therefore, a company's true competitive capacity depends not just on more business but on the ability to build sustainable business with risk control.