New Standard for Financial Statements: Accounting Board Publishes Draft of NFRS 18
The Accounting Board Nepal has published the draft of NFRS 18, a new standard on presentation and disclosure in financial statements. It will bring significant changes to the existing format companies use to present their profit and loss. The board has sought feedback from all stakeholders on the draft.
Kathmandu. The Accounting Board Nepal has published the draft of Nepal Financial Reporting Standards (NFRS) 18. The draft standard, 'NFRS 18, Presentation and Disclosure in Financial Statements,' has been made public with the aim of bringing significant changes to the existing format companies in Nepal use to present their profit and loss.
NFRS is the accounting standard that companies and other entities in Nepal must follow when preparing financial statements. The Accounting Board has been issuing these standards in alignment with those of the International Accounting Standards Board (IASB). The IASB issued International Financial Reporting Standards (IFRS) 18 in April 2024. This standard will come into effect internationally from January 1, 2027. It will replace IAS 1, which has been in use for a long time. NFRS 18 is an effort to adopt that same international standard in Nepal.
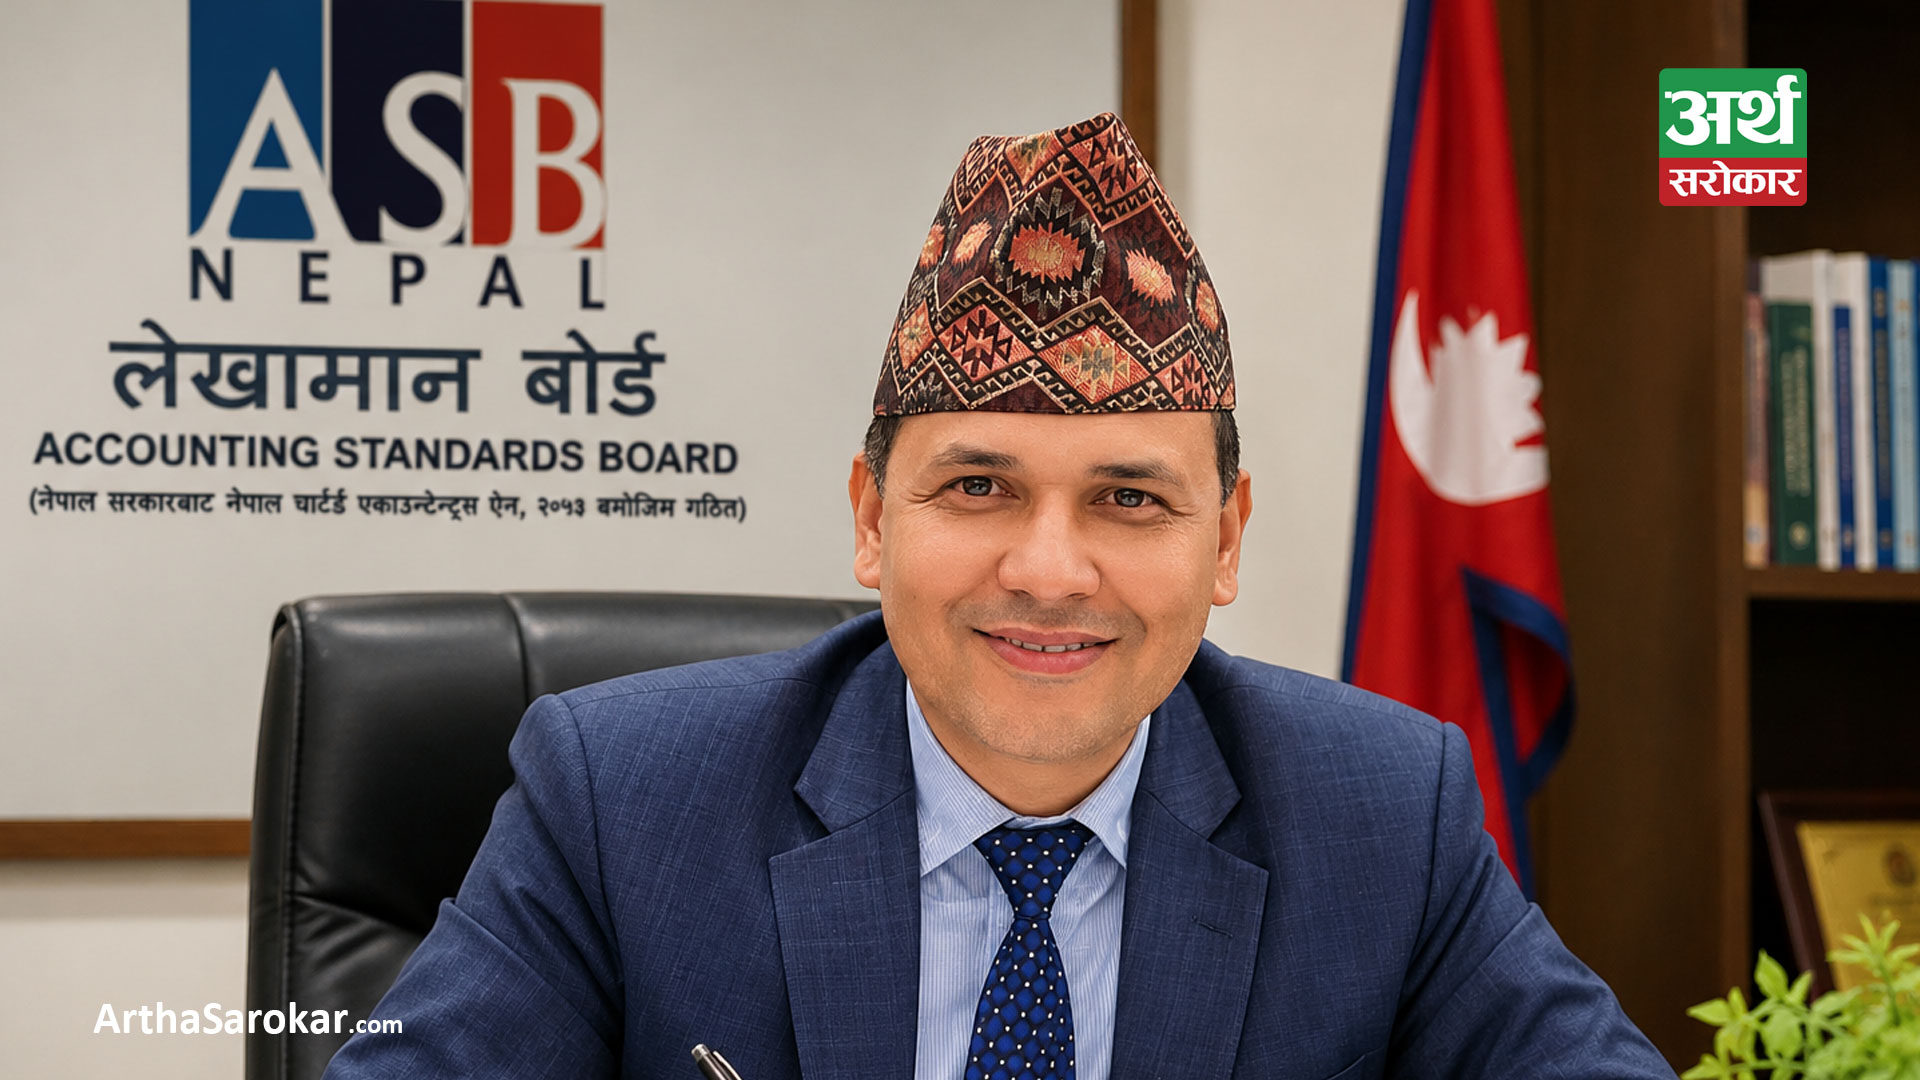
According to Ramesh Kumar Dhital, Chairman of the Accounting Board, NFRS 18 will bring changes to the way companies present their financial statements. Currently, companies show income and expenses in their own ways, making it difficult to compare financial statements. The new provision will require all companies to present income and expenses by classifying them into operating, investing, and financing categories.
Under this, key financial indicators including operating profit must be clearly shown. If a company uses its own measures such as 'adjusted profit,' it must also disclose the basis for that and its relationship with the profit as per the standard.
To implement the new provision, companies may also need to make changes to their accounting and ERP systems. Aligning old data with the new format may take additional time and cost in the initial phase.
For banks, insurance, and investment companies, however, the classification may be somewhat challenging, as their main business is directly related to interest, investment, and financial activities. Therefore, the impact of NFRS 18 will vary depending on the company's business and current accounting system.
The board has sought suggestions from all stakeholders on the draft. The board has stated that the draft will be finalized based on the suggestions and feedback received.