Insurers Warn Annual General Meetings Will Be Delayed Due to NFRS 17 Implementation
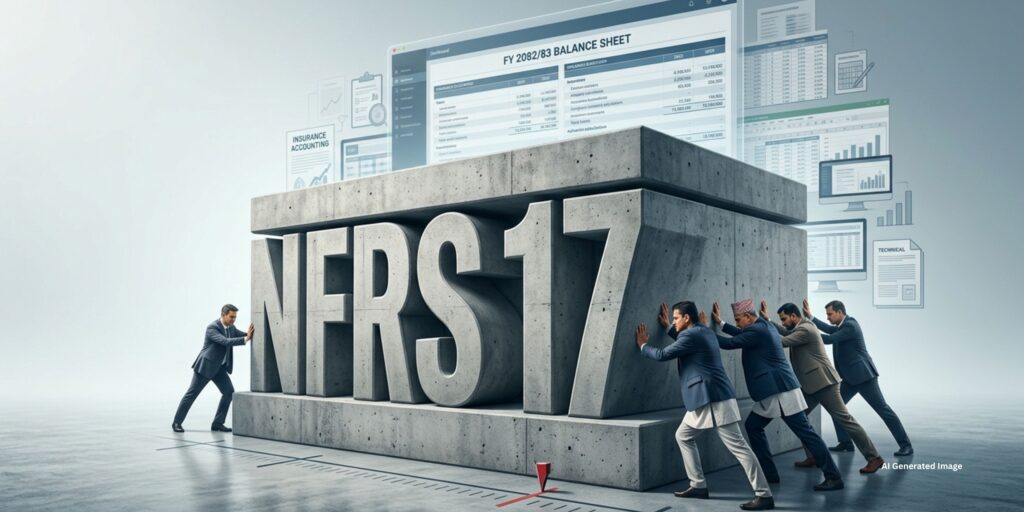
Life insurance companies have warned that most insurers' annual general meetings will be delayed this time due to their inability to implement the new accounting standard NFRS 17. Insurers have pressured to postpone the implementation deadline to the next fiscal year, while the Nepal Insurance Authority remains firm on implementing it according to the predetermined schedule.
Kathmandu. Life insurance companies have warned that most insurers' annual general meetings will be delayed this time due to the implementation of the new accounting standard National Financial Reporting System 17 (NFRS 17).
In a discussion held on Wednesday between the Executive Director of the Nepal Insurance Authority and ten Chief Executive Officers, initiated by the Life Insurers Association, insurers pressured to postpone the implementation deadline of NFRS 17 to the next fiscal year. Insurers made this demand, citing their inability to prepare financial statements and hold general meetings on time due to inadequate preparation for implementing NFRS 17.
According to the provisions of the Insurance Act 2079, insurers must submit actuarial valuations along with annual financial statements and balance sheets to the Authority for approval by the upcoming Poush month. After failing to submit the financial statements and balance sheets for the last fiscal year 2081/82 on time, the Authority fined some insurers up to Rs 200,000 as per the Act's provisions.
The National Accounting Board had issued a directive on NFRS 17 related to insurance contracts, aiming to implement NFRS 17 in Nepal's insurance sector from fiscal year 2080/81. As insurers failed to implement it within the predetermined deadline, the Board has been pressuring insurers through the Authority for its implementation.
The Authority has instructed full implementation of NFRS 17 from the financial statements of the last fiscal year 2082/83. Following the Authority's directive, insurers have also appointed foreign consultants and financial experts. Insurers say there will be challenges in aligning with risk-based capital and self-risk ratio determination structures while implementing NFRS 17.
Since this is being implemented for the first time in Nepal's insurance sector, insurers lack skilled manpower for it. Additionally, the service fees for foreign consultants and technicians preparing financial statements for this system are expensive.
The Authority has provided guidance on NFRS 17 implementation through the 'Guidelines on the Implementation of Nepal Financial Reporting Standard on Insurance Contracts (NFRS 17) for Insurers, 2026 (BS 2083)' (Insurers' NFRS 17 Directive). For its implementation, the Authority has already conducted orientation training, interactions, and training programs on NFRS 17 for insurers' Chief Executive Officers, Chief Financial Officers, and accounting officers, with the involvement of foreign experts.
According to the directive, insurers must prepare financial statements based on both the Insurers' Financial Statement Directive, 2080 and the Insurers' NFRS 17 Directive and submit them to the Authority. However, the general meeting must approve financial statements based on NFRS 17. The directive also requires that the fourth-quarter financial statements of the last fiscal year 2082/83 be prepared and submitted according to NFRS 17 provisions.
Insurers are reluctant to implement this accounting system in the current situation because preparing financial statements based on NFRS 17 will lead to a decline in distributable profits for investors. Previously, when implementing risk-based capital provisions, insurers cited technical problems and inability, but the Authority forced implementation.
Sushil Dev Subedi, Executive Director of the Nepal Insurance Authority, confirmed that a verbal request was received from insurers to extend the deadline for implementing the new accounting standard. He said, 'There is a request from them to postpone to next year as they couldn't prepare financial statements as per NFRS 17.' However, he responded that the Authority is clear about implementing the system according to the predetermined schedule.
The Authority has stated that this system is being implemented to enhance transparency and credibility in the insurance sector, as well as to prepare comparable statements in the insurance sector regarding identification, measurement, and disclosure of insurance contract agreements.