Bhotekoshi Flood: Process and Basic Facts for Advance Insurance Claim Payment to Affected Businesses
The government has announced advance insurance claim payments of up to 50 percent based on preliminary assessment for commercial establishments and industries damaged by the Bhotekoshi flood. This article clarifies the minimum basic facts that insured parties, surveyors, and insurance companies must understand to make claim settlements quick and smooth.
The Bhotekoshi flood is an unimaginable natural disaster for the nation. Various immediate, short-term, and long-term efforts have been and will be made for rescue, relief, reconstruction, and rehabilitation in response to this disaster. In this context, one of the concessions announced by the government to revive commercial establishments and industries damaged by the Bhotekoshi flood is "advance insurance payment."
Under this, it has been announced that insured parties who suffered losses from the flood will immediately receive advance insurance claim payments of up to 50 percent based on preliminary assessment. In this hour of national disaster, everyone must contribute what they can. Accordingly, this article briefly highlights the minimum basic facts that owners, managers, and related social, political, and administrative leaders of insured commercial establishments and industries that suffered losses must necessarily understand to implement the government's insurance claim payment announcement.
Quick and Smooth Insurance Claim Payment: Priority of Insurance Companies and Surveyors
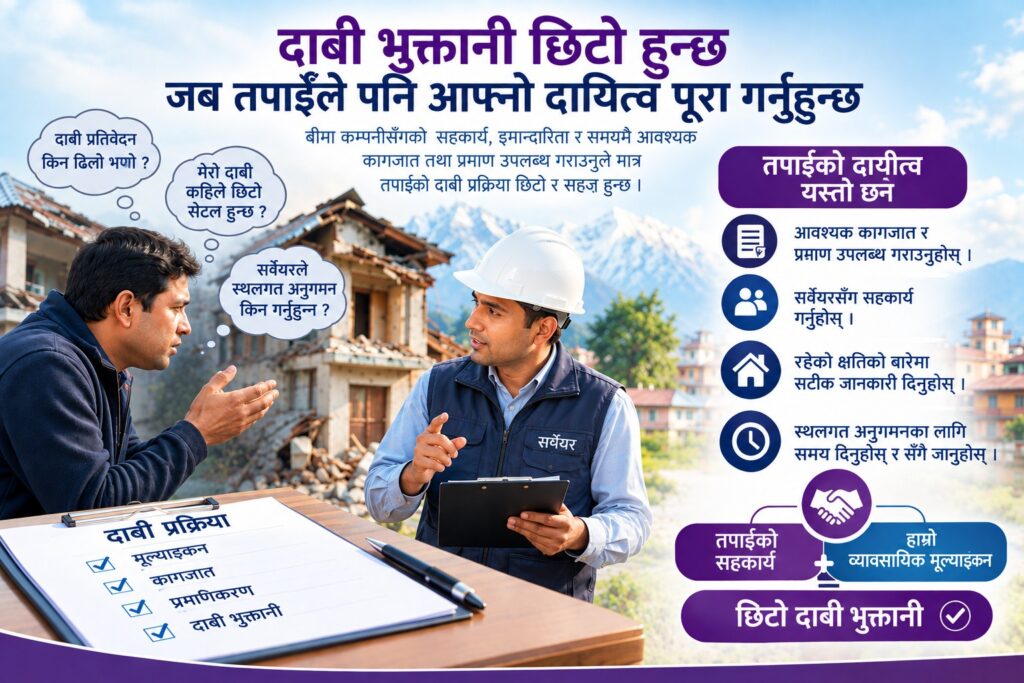
It cannot be entirely denied that due to the incompetence or negligence of insurance surveyors or insurance companies, some insurance claim settlement processes have been left in limbo, potentially resulting in claimants not receiving compensation at all, not receiving fair compensation, or receiving compensation very late. However, most claims are found to be stalled due to a lack of documents that the insured party must provide and that are indispensable for preparing the survey report.
Therefore, it is observed that surveyors are continuously making efforts such as calling claimants to provide the necessary documents, and insurance companies are continuously issuing public notices in newspapers stating "submit documents and settle claims."
Basic Facts Claimants Must Consider Regarding Insurance Claim Payment
In this context, the fact that the general public must consider regarding insurance claim payment is that insurance companies are commercial companies established to do business within the regulatory perimeter. There is no compulsion for the general public to be forced to insure with any one insurance company as if it were a task to be obtained from a government body.
If, even after providing the information and documents demanded by the surveyor, timely or fair compensation is not received, insured parties, in their capacity as customers, are found to warn the insurance company by not renewing the policy or not purchasing additional policies themselves and through their associates. If still dissatisfied with the compensation even after such a warning as a customer, there remains the final option of filing a complaint against the insurance company with the relevant regulatory body, the Nepal Insurance Authority.
However, some claimant insured parties, without realizing the fact that minimum documents are necessary to prepare a loss assessment report, are found to create pressure through related and unrelated bodies or individuals instead of providing documents and information to the surveyor to prepare the loss assessment report. Therefore, the minimum basic aspects that claimant insured parties need to know regarding the documents and information required by the surveyor to prepare the loss assessment report are mentioned here.
Difference Between Bank Loan and Insurance Compensation Disbursement Process
Some members of the general public, understanding the insurance surveyor as an evaluator dispatched by the bank, are found to refuse to provide additional documents demanded by the surveyor and to make statements such as "send the report as it is, whatever the insurance company does, it does." However, there is a fundamental difference between the bank loan and insurance compensation disbursement processes.
The bank disburses loans by taking collateral mortgage to recover the principal amount and agreed interest amount as per the repayment schedule, and to cover the loan amount. In contrast, the insurance company generally pays the compensation amount based on the surveyor's report without performing any of the processes such as taking collateral mortgage to control the person/institution receiving the compensation amount as the bank does, or signing agreements. Thus, while the property valuation report submitted by the bank's valuer to the bank is merely a supporting document for obtaining a bank loan, the loss assessment report submitted by the surveyor to the insurance company is generally a binding document for the insurance company.